
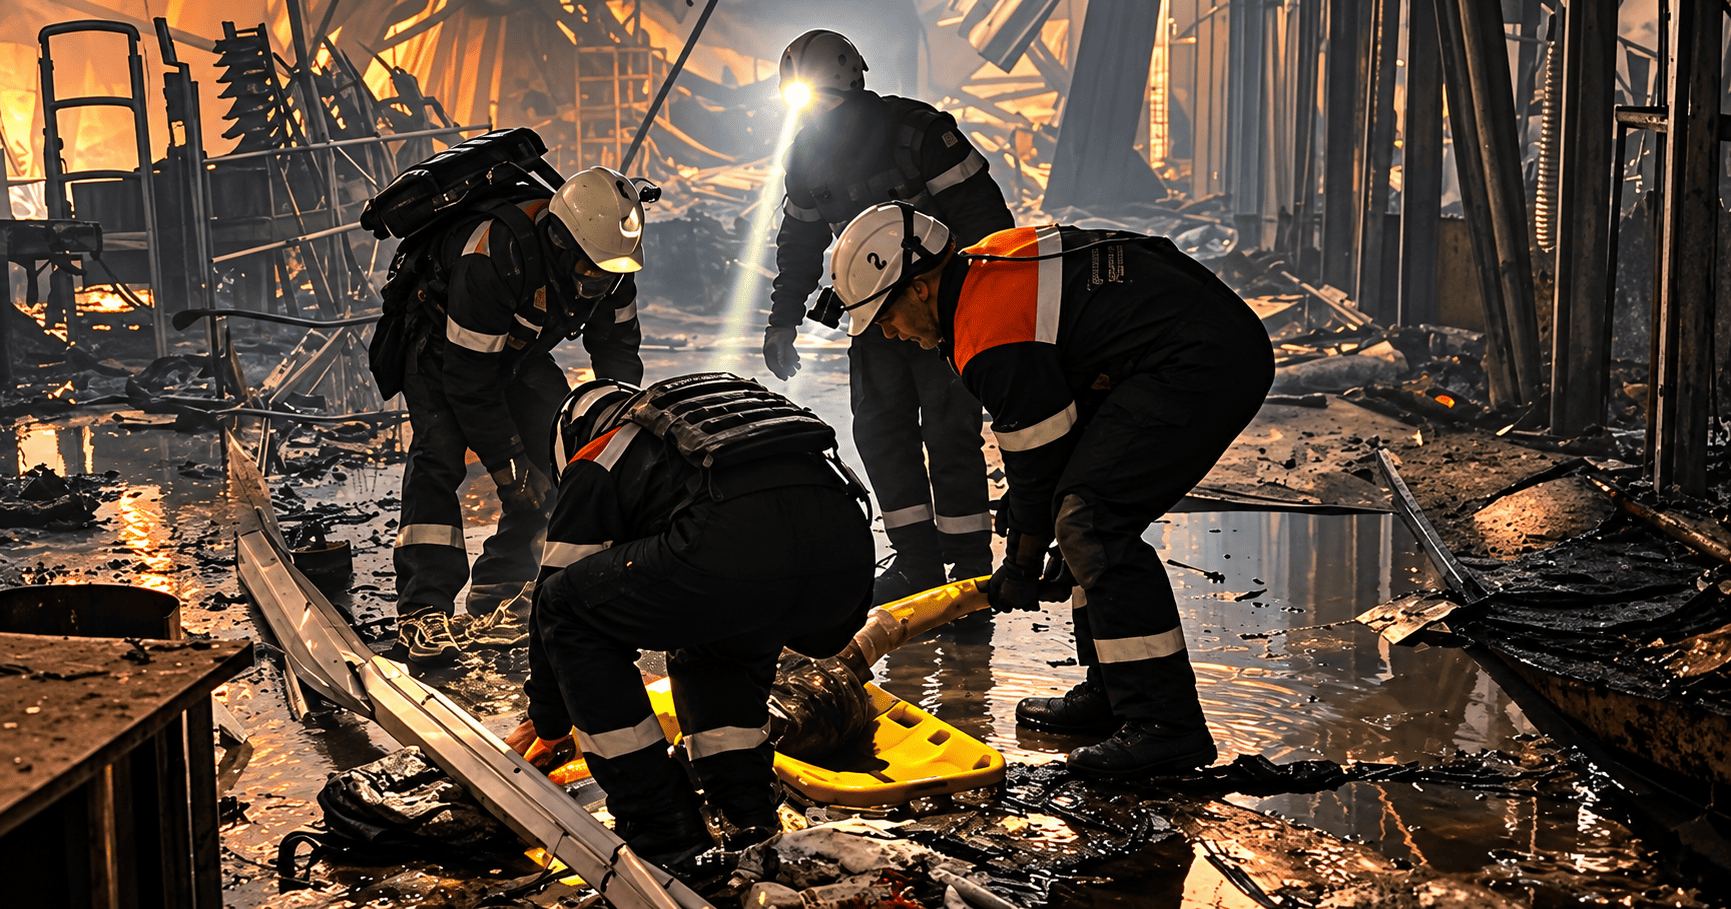
The industrial foundation of Eastern Europe’s heavy manufacturing corridor has suffered a catastrophic disruption as sustained Ukraine steel industry missile strikes brought domestic metallurgical production to an effective standstill. A targeted aerial interdiction campaign conducted by Russian armed forces across August and September systematically struck every operational primary blast furnace facility in Ukrainian-controlled territory. The deliberate destruction of flagship production complexes, including Metinvest’s Zaporizhstal works in Zaporizhzhia and ArcelorMittal’s sprawling facility in Kryvyi Rih, has severed key manufacturing supply chains, threatening hundreds of thousands of industrial livelihoods while eliminating a primary source of sovereign tax receipts.
The neutralization of Ukraine’s primary metallurgy complex delivers severe consequences for wartime economic viability, post-conflict reconstruction planning, and European raw materials supply. Historically recognized as an industrial exporter capable of producing millions of tonnes of crude steel, pig iron, and hot-rolled coils annually, the sector represented a core pillar of macroeconomic stability. For industrial portfolio managers, sovereign debt analysts, and international trade treasurers evaluating how structural physical asset destruction alters continental manufacturing flows, comprehensive reporting across business & finance provides essential intelligence on corporate industrial risk.
Industrial Halts Across Zaporizhzhia and Kryvyi Rih
The scale of the destruction caused by the Ukraine steel industry missile strikes is centered on the nation’s most historic manufacturing hubs. At the Zaporizhstal plant an enterprise employing 8,500 personnel that has anchored Zaporizhzhia’s municipal economy for generations four waves of missile strikes resulted in eight worker fatalities, left 31 wounded, and forced an indefinite operational shutdown:
- Infrastructure Destruction: Russian forces launched 17 cruise and ballistic missiles directly into the Zaporizhstal complex, destroying blast furnace control rooms, blowing out industrial workshops, and puncturing roofs.
- Targeted Retaliation: Metinvest attempted to restart operations, but when engineers reignited a blast furnace, Russian reconnaissance identified thermal activity and launched a secondary strike within ten hours, proving commercial operation unviable.
- ArcelorMittal Kryvyi Rih Closure: On September 25, Ukraine’s largest integrated steelmaker, ArcelorMittal Kryvyi Rih, announced it was permanently unable to reopen after five weeks of continuous bombardment that claimed the lives of five plant employees.
Oleksandr Myronenko, Chief Operating Officer of Metinvest, noted that the strikes represent a deliberate effort to eliminate Ukrainian sovereign solvency: “Clearly, they’re trying to stop Ukraine’s economy and stop Ukraine from getting export money from abroad, from paying taxes and wages, from ensuring that cities live and people have jobs. Their efforts have been very effective so far.”
The physical destruction of foundational production assets, blast furnaces, and coking plants directly wipes out capital formation and sovereign revenue. Economists analyzing how industrial warfare, trade disruption, and labor displacement reshape national output follow macro indicators through regular reporting on the wider economy.
Municipal Budget Crises and Social Fallout
The broader consequences of the Ukraine steel industry missile strikes extend far beyond production floors to threaten municipal solvency. In hosting cities like Kryvyi Rih and Zaporizhzhia, metallurgical enterprises fund between 30% and 70% of municipal budgets.
Local Defense Council head Oleksandr Vilkul warned that the plant shutdowns mean local authorities can no longer finance district heating repairs, maintain communal water networks, or subsidize municipal schools ahead of freezing winter conditions. Stanislav Zinchenko, director of Kyiv-based industrial consultancy GMK Center, underscored that metallurgy was the primary investor in the domestic economy, deploying $2 billion to $3 billion annually. If facilities remain closed, widespread unemployment will prompt accelerated out-migration across Europe.
Sovereign war funding, international financial aid facilities, and territorial reconstruction loans remain critical items across ministerial cabinets. Analysts tracking how legislative assemblies and international bodies coordinate emergency economic packages follow updates via politics.
Port Blockades, Logistics Tracking, and Supply-Chain Settlements
Transporting whatever finished goods survived the Ukraine steel industry missile strikes has become nearly impossible due to ongoing attacks on rail switchyards and Black Sea maritime infrastructure. Commercial bulk carriers loading at Odesa and Chornomorsk face targeted aerial strikes, with shipowners operating under severe insurance restrictions. Logistics software teams are deploying satellite tracking telemetry, automated freight routing, and dynamic port surveillance systems to coordinate emergency overland rail diversions into Central Europe. Technology specialists tracking automated logistics networks follow innovations via tech.
At the same time, regional scrap-metal processing consortia and international trading desks managing cross-border physical deliveries face major banking friction. Corporate treasuries are evaluating programmable settlement rails and crypto networks to execute transparent, escrow-backed settlements for high-value mineral cargoes, bypassing traditional banking delays caused by localized communication outages.
Disrupted steel billet and flat-rolled production flows continue to trigger price volatility and supply squeezes across international industrial markets.
Valuation Impacts on Listed European Steel Equities
The operational paralysis created by the Ukraine steel industry missile strikes reshapes competitive dynamics for publicly traded European steel producers. With Ukrainian exports removed from the market and the European Union enforcing strict import quotas introduced on July 1, continental producers like ArcelorMittal, Salzgitter, and Thyssenkrupp face reduced regional supply, altering pricing power for structural steel and rebar. Institutional equity research desks continuously evaluate scrap-metal input prices, order-book margins, and capacity utilization rates across publicly traded steel and industrial stocks.
According to formal production and capacity audit data compiled by the World Steel Association (worldsteel), the complete cessation of integrated Ukrainian blast furnace production removes millions of tonnes of crude capacity from the global merchant pig iron and semi-finished slab markets.
As plant workers in Zaporizhzhia clear rubble from destroyed machine shops, the aftermath of the Ukraine steel industry missile strikes reveals a devastating economic toll. The systematic elimination of steelmaking leaves Ukraine without a primary economic engine, complicating domestic defense production and post-war reconstruction while forcing international allies to finance municipal survival.
Disclaimer:
The information provided in this article is for educational, journalistic, and informational purposes only and does not constitute financial, investment, industrial procurement, or military defense advice.