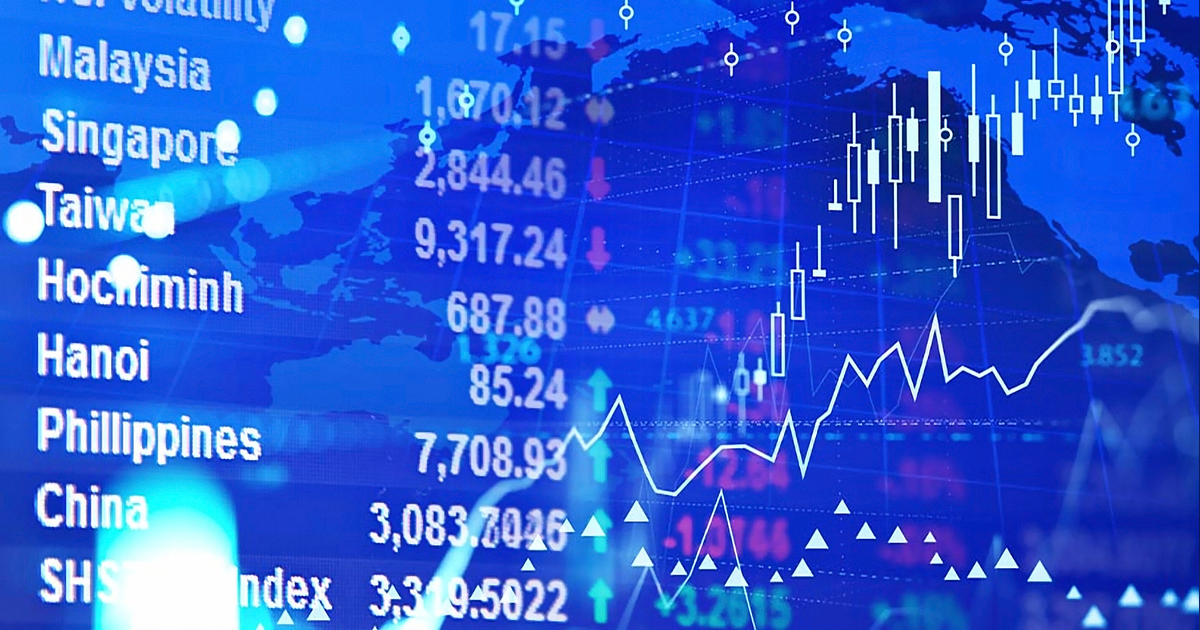
A devastating liquidation swept through international equity markets on Friday as the European Asian stocks tumble AI rout wiped more than $3 trillion in market capitalization from benchmark indexes, triggering emergency regulatory circuit breakers from East Asia to London. The selloff began overnight on Wall Street, where the tech-heavy Nasdaq Composite plunged 5.5% in its worst single-session decline in nineteen months, formally entering technical correction territory. The rout was accelerated by the political fallout from the Democratic sweep of both houses of the United States Congress, which raised concerns that federal lawmakers will increase regulatory scrutiny on hyper-scale infrastructure permits, eliminate data center tax subsidies, and investigate power grid allocations.
The financial contagion traveled rapidly into Asian trading floors before pressuring European bourses at the opening bell. Japan’s Nikkei 225 plummeted 6.0% into technical bear market territory, while equity benchmarks in South Korea and Taiwan registered initial intraday drops exceeding 8%, prompting sovereign finance ministries and central banks to intervene. As European trading got underway, London’s FTSE 100 retreated 1.5%, Frankfurt’s DAX fell 2.2%, and the Paris CAC 40 sank 1.2%. For international multi-asset allocators, macroeconomic hedge fund desks, and institutional credit officers tracking market liquidity conditions, comprehensive European financial news provides critical perspective on cross-border equity valuations, sovereign bond yield curves, and tech sector leverage risks.
The Asian Market Shock: Nikkei Drops 6% and TSMC Hits Circuit Breakers
The initial regional wave demonstrating how European Asian stocks tumble AI rout pressures expanded began across major Pacific semiconductor and hardware exporters:
- Tokyo’s Nikkei Bear Market: The benchmark Nikkei 225 sank 6.0%, marking its steepest single-day decline since April 2025 and pulling the index more than 20% below its summer peak.
- Taipei Circuit Breakers: Taiwan’s benchmark index plunged over 8% after the opening bell before settling down 4.5%, completing a weekly drop of 12.2%—its worst performance since 1991. Foundry bellwether TSMC touched its daily limit-down circuit breaker before finishing 4.7% lower.
- Seoul’s Emergency Interventions: South Korea’s Kospi triggered temporary trading halts as Samsung Electronics dropped 6.0% and SK Hynix fell 9.4%, forcing the Ministry of Finance to relax retail leverage limits.
- SoftBank and Kioxia Plunge: In Tokyo, semiconductor equipment maker Kioxia plunged 11%, while tech holding giant SoftBank Group collapsed 11%, driving the cost of insuring its debt against default to a four-year high.
Official market execution telemetry, index rebalancing schedules, and volatility benchmark reports compiled by Nasdaq demonstrate how tech-heavy capital flows dictate worldwide equity liquidity.
Sovereign bond curves, interbank liquidity spreads, and borrowing costs directly influence corporate capital allocation. Institutional asset managers evaluating advanced infrastructure concessions and public utility balance sheets follow market trends through the InvestorBytes financial portal.
Continental Contagion: European Bourses Retreat as Infrastructure Scrutiny Grows
The macroeconomic transmission showing that European Asian stocks tumble AI rout dynamics crossed the Atlantic visible across primary European exchanges:
- Broad Continental Declines: Germany’s DAX dropped 2.2% in Frankfurt, France’s CAC 40 lost 1.2%, the UK’s FTSE 100 retreated 1.5%, and Dublin’s ISEQ shed 0.6%.
- Semiconductor Supply-Chain Hits: European equipment providers and chipmakers followed international peers lower, with Dutch lithography leader ASML facing heavy selling pressure alongside European utility providers.
- Flight into Sovereign Debt: Institutional capital fled speculative growth equities, triggering heavy inflows into European sovereign bonds and US Treasuries as benchmark yields compressed across maturities.
Corporate debt covenants, secondary offering allocations, and venture technology valuations directly dictate enterprise software execution. Economists evaluating European fiscal governance follow sovereign debt trajectories through InvestorBytes macro reports.
Cabinet deliberations and pan-European industrial policy directives continue to guide continental capital allocations, an area examined in European policy updates.
The Core Catalyst: Slower Data Center Build-Outs and Political Friction
A central driver behind the European Asian stocks tumble AI rout centers on rising regulatory and infrastructure costs for artificial intelligence hardware:
- The Legislative Pivot in Washington: With Democrats securing majorities in the US Senate and House of Representatives, investors anticipate legislative probes into data center grid consumption and water utilization.
- Local Opposition and Moratoriums: Texas Governor-elect Gina Hinojosa pledged statutory protections for local communities against rapid data center expansion, matching local voter initiatives that opposed data centers in 40 of 41 municipal ballot measures.
- Strains at Specialized Providers: High-performance cloud provider CoreWeave dropped 10%, while its five-year credit default swap (CDS) spreads widened to historic highs, reflecting mounting funding costs for heavily leveraged compute providers.
- Shattered Growth Illusions: Market commentators noted that equity valuations had priced in uninterrupted double-digit infrastructure growth, leaving balance sheets exposed once political hurdles, high energy tariffs, and high interest rates converged.
Corporate financial controllers and enterprise procurement directors monitoring data center hardware supply chains follow market pricing trends on the InvestorBytes homepage.
The complex relationship between rising industrial electricity rates, hardware depreciation schedules, and corporate operating margins is evaluated in InvestorBytes corporate analysis.
Financial Telematics, Algorithmic De-Risking, and Margin Call Liquidation
Navigating the cross-asset volatility resulting from the European Asian stocks tumble AI rout requires advanced execution telematics. Institutional prime brokers and high-frequency market-making firms deploy automated margin-call liquidation scripts, algorithmic cross-venue dark pools, and multi-asset hedging modules to process heavy volume spikes. Technology specialists tracking smart energy management systems follow system architectures through InvestorBytes digital finance.
Concurrently, European public utility providers and regional transmission system operators managing industrial cooling loads face grid-stability challenges during synchronized facility resets. Infrastructure syndicates are deploying real-time telemetry ledgers and smart microgrid interfaces to coordinate on-site renewable energy generation with grid off-take, an operational evolution documented in international capital analyses.
Shifting capital distributions and sovereign regulatory changes continue to influence liquidity across energy and industrial desks tracked in continental market coverage.
Capital Market Implications for Tech Valuations and Credit Spreads
The market repricing crystallized as the European Asian stocks tumble AI rout unfolds introduces significant strategic adjustments for global institutional allocators. While some market technicians argue that limit-down circuit breakers across foundry leaders indicate the final stages of speculative capitulation, corporate balance-sheet realities remain altered. Capital expenditure allocations across hyperscalers will face rigorous return-on-investment thresholds from shareholders, constraining borrowing by smaller infrastructure developers. Concurrently, debt investors are demanding wider risk premiums across technology corporate paper. Institutional equity research desks continuously evaluate forward price-to-earnings multiples, consumer demand elasticity, and corporate earnings durability through InvestorBytes equity intelligence.
Corporate financial executives, private wealth managers, and institutional asset allocators track macroeconomic risk pricing and market sentiment via the InvestorBytes publication.
As equity markets conclude a volatile trading week, the fallout from the European Asian stocks tumble AI rout marks the end of unconstrained multiple expansion for artificial intelligence equities. By forcing hardware providers and utility operators to demonstrate commercial returns and reconcile energy constraints with local regulations, global markets are transitioning into an era where balance-sheet fundamentals outweigh speculative momentum.
Disclaimer:
The information provided in this article is for educational, journalistic, and informational purposes only and does not constitute financial, investment, legal, tax, or equity trading advice.