
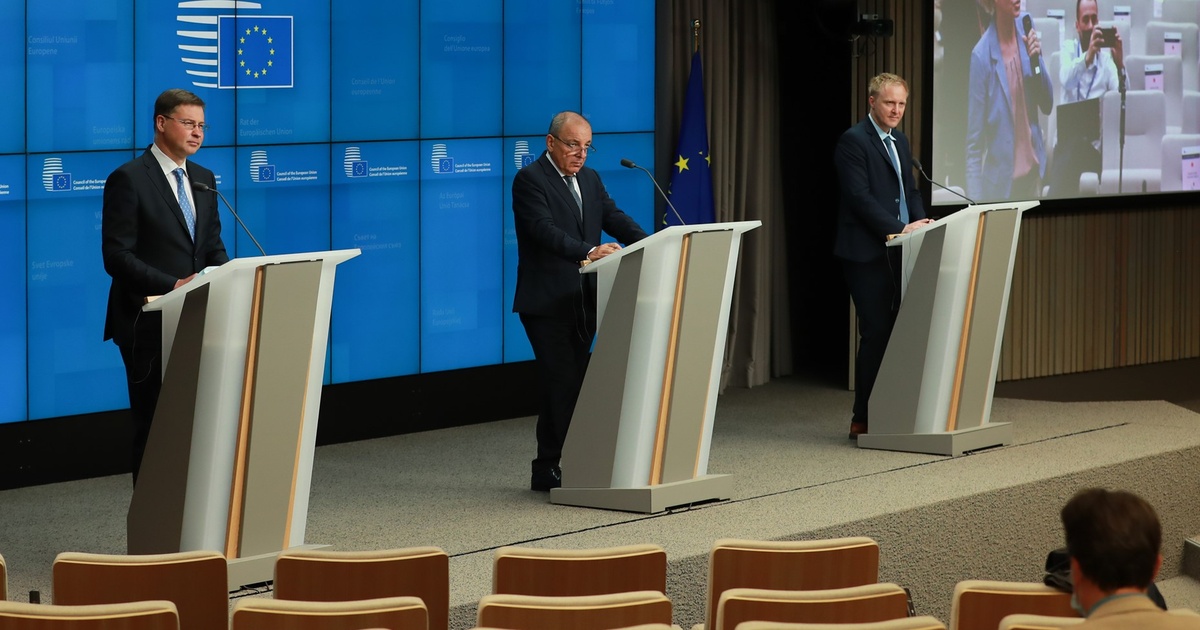
A comprehensive regulatory reassessment is sweeping across the continent’s financial institutions as European Union finance ministers evaluate an extensive EU banking overhaul designed to eliminate multi-billion-euro compliance redundancies. Convening for high-level ministerial negotiations in Dublin, economic leaders reviewed an official European Commission roadmap targeting structural supervisory overlaps, reporting friction, and fragmentation across member states. Disclosing the core findings of the report, European Commission Executive Vice-President Valdis Dombrovskis revealed that administrative reporting obligations currently impose an annual €11.2 billion overhead directly onto European banks.
The drive to streamline financial operations carries profound systemic ramifications for sovereign credit markets, regional lending capacity, and commercial competitiveness. When compliance overheads consume substantial operational expenditure, domestic institutions struggle to generate competitive returns on equity against American and Asian financial giants. For institutional risk officers, treasury executives, and corporate directors analyzing how changing statutory mandates alter enterprise governance, regular newsroom reporting on business & finance provides indispensable intelligence on continental banking reform.
Unpacking the €11.2 Billion Burden: The Core Drivers of the Overhaul
The foundational catalyst driving this EU banking overhaul is the recognition that years of post-crisis regulation have created excessive administrative friction. Dombrovskis highlighted that while the EU’s post-2008 prudential framework successfully reinforced bank capitalization and liquidity buffers, successive waves of legislative reforms generated severe duplication across overlapping regulatory authorities.
With reporting costs estimated at €11.2 billion annually, lenders find themselves submitting repetitive datasets to national central banks, the Single Supervisory Mechanism (SSM), the European Banking Authority (EBA), and regional resolution bodies.
“We remain committed to implementing international standards for banking regulation and will not lower the bar,” Dombrovskis informed delegates, “but we want standards applied in a way that reflects Europe’s specific circumstances”.
Priorities for Rationalizing Capital and Compliance
Ministers outlined several critical structural adjustments to restore European institutional competitiveness:
- Eliminating Supervisory Overlaps: Merging redundant reporting templates across prudential, conduct, and resolution watchdogs into centralized data gateways.
- Proportionality for Mid-Tier Lenders: Tailoring reporting frequency and granular disclosure rules so that community and regional commercial banks are not penalized by standards designed for global systemically important institutions.
- Cross-Border Market Integration: Dismantling national ring-fencing rules on liquidity and capital to allow integrated institutions to deploy funds freely across the single currency area.
Easing structural compliance frictions directly influences capital availability for small and medium-sized enterprises (SMEs) and heavy industrial infrastructure. Economists tracking how credit conditions and financial regulations shape continental gross domestic output can follow cyclical developments via comprehensive coverage of the wider economy.
Integrating Distributed Ledgers, Tokenization, and Digital Settlement
A major dimension of the proposed EU banking overhaul centers on modernizing transactional rails and capital distribution platforms. Finance ministers held extensive working sessions on financial innovation, evaluating advances in digital payments, syndicated lending, and capital markets tokenization.
Dombrovskis specifically pointed to the accelerated deployment of distributed ledger technology (DLT) across sovereign bond issuances and institutional wholesale payments. While ministers agreed that innovation requires robust consumer safeguards and legal certainty, there is growing momentum to provide pan-European regulatory sandboxes that allow institutions to test asset tokenization at commercial scale.
At the same time, institutional treasuries navigating cross-border clearing frictions are increasingly utilizing modern digital asset architectures. As global settlement demands 24/7 liquidity, leading commercial desks evaluate decentralized protocols, asset-backed stablecoins, and crypto networks to streamline wholesale transfers and minimize interbank transaction latency.
Regulatory clarity around digital ledgers and cross-border lending is reshaping institutional liquidity across European markets.
Managing Artificial Intelligence Risks and Legislative Safeguards
The ongoing EU banking overhaul incorporates artificial intelligence into core systemic oversight for the first time. The Dublin discussions were informed by a specialized briefing delivered by International Monetary Fund (IMF) Managing Director Kristalina Georgieva, who detailed both the productivity advantages and systemic vulnerabilities introduced by autonomous models in finance.
Ministers addressed the urgent necessity of deploying a “concrete, workable and robust” regulatory framework for financial AI applications. Key risks evaluated included:
- Algorithmic trading feedback loops that could destabilize sovereign debt markets during liquidity freezes.
- Supply-chain dependencies on concentrated cloud hosting and proprietary third-party foundation models.
- Downstream macroeconomic impacts across high-skilled labor markets and grid power consumption driven by energy-intensive data centers.
To evaluate how machine-learning credit algorithms, automated regulatory technology (RegTech), and neural compliance software are transforming banking operations, technology specialists follow developments through specialized reporting on tech.
Simultaneously, the convergence of AI supervision, fiscal harmonization, and financial sovereignty remains a contentious legislative topic across European capitals. Analysts tracking how ministerial debates and parliamentary directives govern continental institutions can examine policy shifts via politics.
Equity Realities for Listed European Banking Groups
The multi-year timeline of the EU banking overhaul introduces meaningful valuation catalysts for publicly traded lenders. Eliminating even a fraction of the €11.2 billion in annual reporting waste could immediately expand operating margins, driving returns on equity toward levels long enjoyed by Wall Street peers. Equity research analysts continuously monitor these cost-to-income improvements, regulatory capital releases, and dividend sustainability metrics across major European financial stocks.
According to formal supervisory guidelines published by the European Banking Authority (EBA), streamlining reporting frameworks without diluting underlying Basel III solvency buffers represents the central challenge for European regulators over the coming cycle.
As Dombrovskis confirmed that reform consultations will intensify in the months ahead, the proposed EU banking overhaul marks a critical turning point. By confronting €11.2 billion in administrative bloat while integrating tokenization and AI governance, European authorities are attempting to construct a modern financial architecture capable of competing globally.
Disclaimer:
The information provided in this article is for educational, journalistic, and informational purposes only and does not constitute financial, investment, regulatory compliance, or legal advice.