A structural transformation of historic proportions is sweeping across the continent as the Europe car industry crisis moves beyond transition bottlenecks into an existential fight for survival. European automotive titans are grappling with high energy tariffs, aggressive competition from Chinese brands, declining margins, and widespread factory overcapacity. As major manufacturers announce painful restructurings, a wartime geopolitical reality is opening an unexpected industrial avenue. With European nations accelerating defense rearmament, governments and manufacturers are asking whether sovereign defense production can absorb idle automotive capacity.
The potential reallocation of industrial facilities carries enormous consequences for labor markets, regional trade flows, and manufacturing infrastructure. For decades, Europe’s economic dominance was underpinned by precision automotive engineering and export-led assembly lines. However, as global vehicle demand shifts, retooling idle production capacity toward military hardware could redefine sovereign manufacturing. For corporate treasurers, supply chain directors, and institutional investors analyzing how industrial realignment alters asset valuations, regular newsroom reporting on business & finance provides indispensable intelligence on enterprise restructuring.
Structural Overcapacity and the Chinese EV Surge
The foundational catalyst behind the Europe car industry crisis is a compounding combination of slowing demand and fierce overseas competition. Volkswagen, Europe’s largest automotive group, has embarked on the most aggressive downsizing plan in its corporate history, with approximately 100,000 workforce reductions linked to its long-term modernization roadmap. The automaker is wrestling with substantial excess manufacturing capacity, shrinking profitability, and deteriorating market share in China.
This industrial contraction extends across the continent. In Germany alone, the domestic automotive sector lost 42,300 jobs in the twelve months leading to June, reflecting widespread layoffs across component suppliers and tier-one engineering firms.
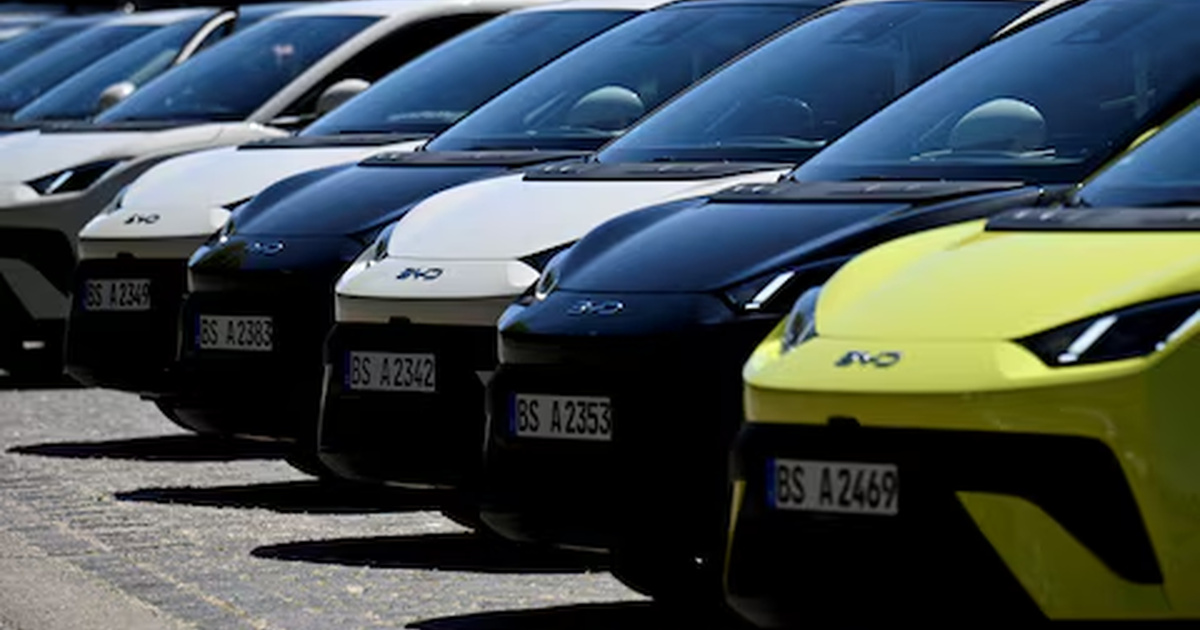
Simultaneously, Chinese automakers have accelerated their European expansion. Chinese-branded vehicles captured roughly 9% of all European Union vehicle sales during the first half of 2026. Rather than relying solely on maritime imports, manufacturers such as BYD, Chery, and Geely are building or acquiring assembly hubs across Europe. In an illustration of the continent’s excess capacity, Stellantis opened portions of its European production footprint to Chinese partners to keep facilities running, underscoring that Europe has factories and workers, but lacks profitable domestic models to sustain them.
The contraction of automotive output directly affects domestic taxation, manufacturing employment, and sovereign growth. Economists evaluating how industrial downsizing and factory retooling alter continental gross domestic output can follow long-term indicators through dedicated reporting on the wider economy.
The Defense Pivot: Repurposing Auto Plants for Rearmament
As European governments ramp up sovereign military budgets to counter regional aggression and offset potential transatlantic defense shifts, the Europe car industry crisis is intersecting with military procurement. Sovereign defense programs face acute shortages of precision engineering facilities, robotics, and advanced materials.
Volkswagen’s Osnabrück assembly plant has emerged as an early case study for this industrial pivot. Scheduled to halt passenger vehicle production by 2027, the facility is being evaluated for conversion into a defense production site. Under a proposed framework involving Aurelius Capital and the state government of Lower Saxony, approximately 1,400 of the plant’s 1,800 manufacturing jobs could be preserved by retooling the factory to produce components for air-defense missile systems.
The overlap between automotive manufacturing and modern defense hardware makes this transition practical. Modern military contracts require precision machining, high-capacity battery systems, sensor arrays, advanced robotics, and complex wiring harnesses—capabilities already perfected by automotive suppliers.
The retooling of industrial capacity directly alters regional capital flows, sovereign bond issues, and sector rotations across public markets.
Policy Directives: The Industrial Accelerator Act and Trade Shields
Navigating the Europe car industry crisis requires more than individual factory conversions; it demands a coordinated supranational industrial policy. The European Commission has advanced legislative proposals under the Industrial Accelerator Act, incorporating strict “Made in EU” provisions designed to shield domestic supply chains and reduce reliance on Chinese imports in critical industries.
Brussels is also evaluating emergency import quotas on Chinese plug-in hybrid models to prevent foreign manufacturers from circumventing battery-electric tariffs. Observers analyzing how supranational trade defenses and ministerial directives govern industrial subsidies can examine statutory developments via politics.
At the same time, high-tech engineering firms converting production lines to military hardware rely on advanced digital automation. Engineers deploy algorithmic digital twins, real-time sensor analytics, and automated robotics to meet rigorous military specifications. Technology professionals tracking these production systems follow technical innovations via tech.
Concurrently, multinational defense contractors and tier-one automotive suppliers managing multi-jurisdiction procurement are exploring modern financial infrastructure. Corporate treasuries evaluate programmable liquidity protocols and crypto networks to settle cross-border parts deliveries and automate escrow payments across complex supply networks.
Equity Market Realities for Automotive and Defense Shares
The evolving response to the Europe car industry crisis creates contrasting valuations for public equities. Traditional automakers carrying high legacy overheads face compressed price-to-earnings multiples and dividend cuts. Conversely, automotive component suppliers that successfully secure defense subcontracts stand to stabilize cash flows and expand backlogs. Institutional investors closely monitor corporate debt loads and operating margins across European industrial stocks.
According to formal industrial policy recommendations published by the European Commission, preserving Europe’s high-tech manufacturing base is vital to maintaining continental economic sovereignty.
Converting car factories into defense plants cannot replace the entire passenger vehicle market. However, as the Europe car industry crisis tests the viability of legacy manufacturing, military rearmament offers a pragmatic bridge. By transitioning idle assembly lines into defense production, Europe may preserve the skilled engineering workforce and industrial base built over the last century.
Disclaimer:
The information provided in this article is for educational, journalistic, and informational purposes only and does not constitute financial, investment, automotive, or military defense procurement advice.