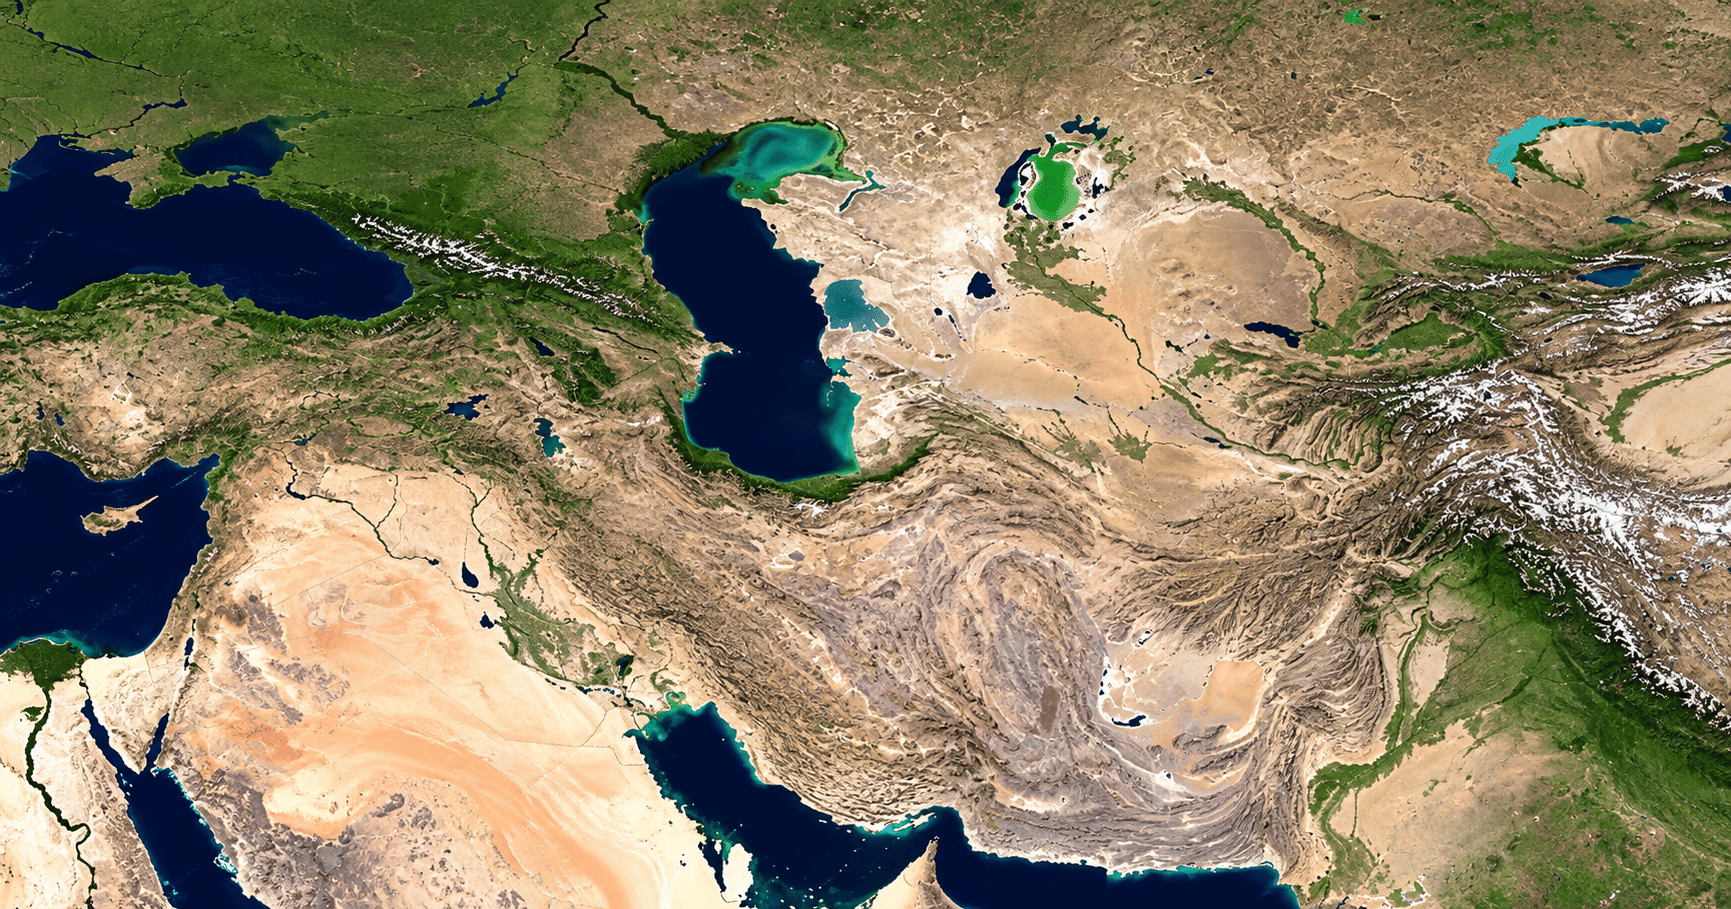
A profound structural transition is reshaping continental supply networks as Europe Central Asia trade corridor risks emerge across regulatory, environmental, and financial dimensions. While bilateral commerce between European trade hubs and Central Asian republics continues to expand in nominal value, the operational mechanisms underpinning cross-border transactions face mounting headwinds. The Netherlands has solidified its position as the primary European destination for Kazakh exports, yet this trade remains overwhelmingly asymmetrical: crude oil flows westward through maritime infrastructure, while European capital goods, machinery, and specialty pharmaceuticals travel eastward.
However, beneath top-line trade volumes lies a complex matrix of operational friction. Importers, international credit underwriters, and logistics operators must navigate the definitive rollout of the European Union’s Carbon Border Adjustment Mechanism (CBAM), expanding secondary sanctions enforcement, physical capacity bottlenecks along the Trans-Caspian route, and alternative non-Western clearing channels. For corporate treasurers, supply chain directors, and commercial risk analysts evaluating these structural trade pressures, comprehensive European financial news provides indispensable insight into supply chain security and international commerce.
The Dutch-Kazakh Trade Asymmetry: One Commodity Moving West
The primary commercial baseline illustrating Europe Central Asia trade corridor risks is the deep structural imbalance defining Dutch-Kazakh exchange. According to official customs returns recorded in the United Nations Comtrade database, Kazakhstan exported $5.30 billion of goods to the Netherlands in 2024, with mineral fuels and hydrocarbons accounting for $5.18 billion, or approximately 98% of the aggregate total. Conversely, Dutch shipments heading eastward totaled $972.9 million in 2025, comprising high-value manufactured machinery, mechanical appliances, automotive vehicles, aerospace equipment, and advanced pharmaceuticals:
- Distinct Financing Profiles: Western-bound crude oil moves under established commodity contracts backed by mature hedging instruments, whereas eastern-bound industrial machinery relies on documentary letters of credit facing strict end-use scrutiny.
- The Rotterdam Refining Hub: Much of the crude registered as Dutch trade does not remain in the domestic economy; it arrives at the Port of Rotterdam for industrial refining or blending before re-export across Western Europe.
- Pipeline Transit Vulnerability: Despite ongoing diplomatic dialogues surrounding alternative overland corridors, the vast majority of Kazakh crude over 63 million of the 99.6 million tonnes produced in 2025 continues to transit via the Caspian Pipeline Consortium line to the Russian port of Novorossiysk.
Understanding how raw commodity flows interface with specialized export financing is essential for cross-border banking institutions. Analysts monitoring how export dependencies affect continental corporate liquidity follow market developments through the InvestorBytes financial portal.
CBAM Implementation: The Near-Term Repricing of Industrial Exports
The most immediate regulatory factor driving Europe Central Asia trade corridor risks is the definitive enforcement of the EU Carbon Border Adjustment Mechanism, which entered its full regulatory regime on January 1, 2026. Designed to equalize carbon pricing between domestic production and foreign imports, the regulation directly targets carbon-intensive commodities entering the single European market.
The commercial exposure for regional manufacturers is severe:
- The Cost of Carbon: Following the quarterly benchmark set on April 7, 2026, the European Commission established the CBAM certificate price at €75.36 per tonne of CO2 equivalent, aligned with auction clearing prices in the EU Emissions Trading System (ETS).
- Kazakh Industrial Exposure: A joint assessment conducted by the International Trade Centre and QazTrade revealed that Kazakhstan exports over €600 million of steel and aluminium to the EU annually; without audited, installation-level emissions data, default penalties could exceed €100 million annually.
- Product Margin Wipeout: In specific high-carbon steel bars and rods, unverified default carbon surcharges threaten to exceed the baseline commercial value of the underlying product by up to 123%.
- The Cash-Flow Timing Gap: While carbon liabilities begin accruing upon physical import, formal certificate purchases cannot be executed until February 2027 ahead of the September 2027 surrender deadline, creating an awkward financing gap that commercial importers must fund.
Navigating these regulatory levies forces industrial exporters to invest heavily in accredited emissions auditing, a challenge evaluated across InvestorBytes macro reports.
Statutory environmental adjustments and regional border tariffs continue to reshape international trade relationships, an issue tracked within European policy updates.
The Trans-Caspian Corridor: Capacity, Water Levels, and Rail Caps
Logistical efforts to mitigate Europe Central Asia trade corridor risks have elevated the Trans-Caspian International Transport Route (TITR), commonly termed the Middle Corridor, into a critical alternative to northern Russian rail networks. However, freight statistics indicate that infrastructure constraints continue to limit its aggregate throughput.
Kazakh Ministry of Transport records show that overall cargo volumes across the corridor reached 4.12 million tonnes in 2025, down roughly 8% from 4.48 million tonnes in 2024. While container traffic rose 36% to approximately 77,000 TEU, the route faces physical and environmental challenges:
- Falling Caspian Water Levels: Driven by climate shifts, the Caspian Sea has receded by more than half a meter over the past five years, forcing commercial cargo vessels to operate at 75% to 80% capacity and necessitating continuous port dredging.
- Transit Duration and Cost: Multi-modal transport times currently range between 18 and 23 days, carrying costs of $2,500 to $3,250 per 40-foot container, compared to $1,500 to $2,000 for slower maritime transit.
- Asymmetrical Port Facilities: While the Azerbaijani port of Alat handles up to 150,000 TEU with expansion plans targeting 260,000 TEU, Kazakh terminals at Aktau and Kuryk face tighter throughput thresholds.
Corporate freight forwarders assessing multi-jurisdiction transport insurance follow infrastructure logistics updates on the InvestorBytes homepage.
Logistical bottlenecks and multi-modal transit friction across Central Asian corridors are examined regularly in InvestorBytes corporate analysis.
Sanctions Enforcement, End-Use Screening, and Banking Compliance
The sharpest trade finance exposure within the Europe Central Asia trade corridor risks landscape centers on secondary sanctions compliance. As regulatory enforcement agencies in Brussels, Washington, and London target circumvention routes, Central Asian commercial intermediaries face unprecedented scrutiny.
Sanctions enforcement has created clear jurisdictional distinctions across the region:
- The Kyrgyz Designations: The EU’s 20th sanctions package in April 2026 enforced transaction bans on Keremet Bank and Capital Bank of Central Asia, while activating the EU’s anti-circumvention tool to prohibit shipments of advanced machine-tooling centers.
- Kazakh Banking Insulation: Systemic Kazakh and Uzbek domestic commercial banks have avoided direct statutory designations, although localized trading entities and Russian-owned subsidiaries have faced asset freezes.
- Mandatory Export Clauses: Article 12g of EU Regulation 833/2014 legally mandates that European exporters incorporate strict “no re-export to Russia” contractual representations when shipping sensitive equipment and Common High Priority Items.
International trade finance institutions managing letter-of-credit issuance and counterparty due diligence follow compliance trends through InvestorBytes digital finance.
Risk assessment teams analyzing compliance mandates and cross-border documentary credit requirements review detailed frameworks in international capital analyses.
Sovereign foreign exchange volatility and clearing regulations across emerging trade channels are monitored via continental market coverage.
The Emergence of Alternative Renminbi Settlement Rails
A defining development altering Europe Central Asia trade corridor risks is the expansion of non-Western clearing channels. Regional sovereign entities are diversifying access to capital by tapping Chinese domestic debt and liquidity mechanisms.
In April 2026, Kazakhstan’s sovereign wealth fund Samruk-Kazyna issued the region’s inaugural sovereign-linked panda bond, following offshore renminbi issuances by the Development Bank of Kazakhstan and energy group KazMunayGas. With national external debt to Chinese creditors climbing past $12.87 billion, Central Asian borrowers maintain growing access to alternative renminbi liquidity channels that operate independently of Western financial clearing systems, an evolution tracked via InvestorBytes equity intelligence.
Corporate treasurers and trade financiers monitor these shifting monetary channels and debt instruments through the InvestorBytes publication.
As the February 2027 CBAM purchasing cycle approaches, navigating Europe Central Asia trade corridor risks requires careful adaptation. Exporters and financiers who integrate verified emissions tracking, strict compliance documentation, and diversified logistical routes will be best positioned to sustain viable commercial trade between Europe and Central Asia.
Disclaimer:
The information provided in this article is for educational, journalistic, and informational purposes only and does not constitute international trade, legal, compliance, or financial investment advice.