A striking divergence in continental property valuations emerged on Friday as European house prices rise by an aggregate 4.7% year-on-year across the European Union during the second quarter of 2026. According to the latest harmonized House Price Index released by Eurostat, residential real estate values outpaced the bloc’s headline inflation rate of 3.2%, demonstrating sustained underlying demand despite tighter monetary conditions. However, beneath the headline average lies a fragmented continent: nine separate jurisdictions recorded double-digit annual price growth led by Portugal and Bulgaria, while core economies including France and Finland saw prices contract.
The structural divide illustrates how national supply constraints, international capital inflows, and demographic shifts outweigh uniform monetary policy across the euro area. While the European Central Bank maintains elevated borrowing costs, persistent structural housing shortages continue to push acquisition costs higher across prime metropolitan and Mediterranean markets. For institutional property underwriters, mortgage syndicates, and real estate investment trusts evaluating continental asset allocations, comprehensive European financial news provides vital perspective on macroeconomic resilience and real estate trends.
Double-Digit Surges: Portugal, Bulgaria, and the Mediterranean Outliers
The primary momentum explaining why European house prices rise so aggressively is concentrated in Southern and Eastern European economies. Nine countries recorded annual increases exceeding 10%, driven by intense buyer demand and acute supply bottlenecks:
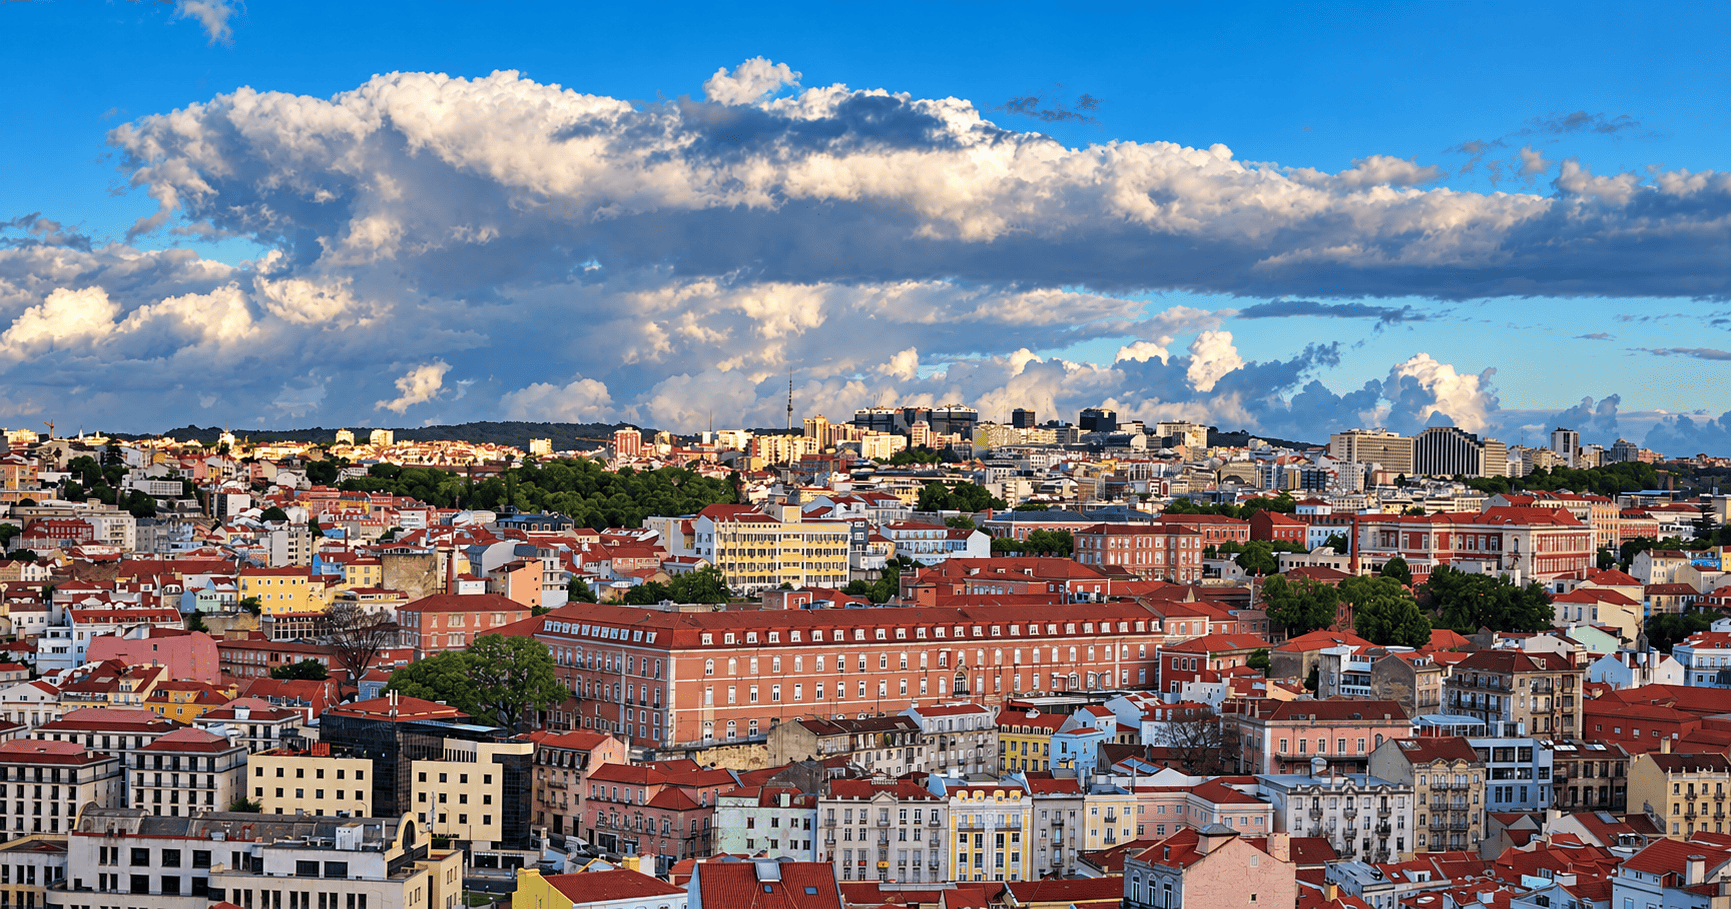
- Portugal Leads the Bloc: Portugal posted the European Union’s steepest annual home price appreciation at 16.5%. In prime urban centers such as Lisbon and Porto, persistent supply deficits, foreign buyer demand, and tourism conversions have driven property costs higher.
- Bulgaria’s Investment Boom: Bulgaria registered a 15.5% annual increase, supported by robust real wage growth, rising household disposable incomes, and strong demand for residential real estate as a hedge against inflation.
- Baltic and Central European Gains: Lithuania followed with a 14.3% rise, Slovakia expanded by 13.6%, Croatia climbed 12.7%, and Romania increased 12.1%.
- Spain’s Ongoing Expansion: Spain registered a 12.1% surge, while Latvia posted 11.4% and Hungary rounded out the double-digit group at 10.2%.
“Limited new construction, foreign investment, tourism-related demand and persistent housing shortages have all contributed to rising prices,” noted Mikk Kalmet, real estate specialist at Global Property Guide.
Surging residential asset values directly impact household net worth, mortgage origination volumes, and domestic consumer expenditure patterns. Readers assessing commercial balance sheets, banking risk profiles, and private-sector treasury liquidity can evaluate deeper corporate intelligence through the InvestorBytes financial portal.
Core Market Contractions: France, Finland, and German Stagnation
In sharp contrast to the Southern surge, European house prices rise narratives do not apply uniformly across the continent’s largest economies. Three member states recorded outright annual contractions:
- Finland (-2.7%): Weak domestic GDP expansion, subdued consumer confidence, and high debt-service ratios among households pulled transaction values lower.
- Luxembourg (-2.2%): Elevated initial property valuations combined with restrictive underwriting standards curtailed institutional and retail buyer appetite.
- France (-0.8%): Severe affordability constraints and elevated borrowing costs suppressed transaction volumes, mirroring broader sovereign fiscal strain tracked on InvestorBytes market reports.
Meanwhile, Germany managed an anemic 0.6% annual increase, held back by weakening mortgage applications and consumer hesitancy.
Municipal property taxes, statutory rent-control legislation, and residential zoning regulations remain central topics across European assemblies. Observers monitoring how legislative chambers and ministries govern housing policy follow regulatory developments via European policy updates.
Real Price Trajectories: Beating Inflation Benchmarks
When adjusted for consumer price inflation, the reality that European house prices rise reveals significant real-term equity accumulation for property owners across selective jurisdictions. Across the broader European Union, real house price growth stood at 1.5%.
However, real growth exceeded 7% across multiple jurisdictions:
- Slovakia: 9.4% real growth.
- Bulgaria: 9.1% real growth.
- Lithuania: 8.8% real growth.
- Spain: 8.3% real growth.
- Portugal: 12.1% real price growth against domestic inflation of 3.6%.
Conversely, six countries posted real price declines, led by Luxembourg (-6.4%), France (-3.2%), and Germany (-2.0%). These shifts highlight how domestic cost structures vary across the continent, an important consideration for expatriates exploring international relocation guides featured on the InvestorBytes homepage.
Automated Valuations, PropTech, and Digital Mortgage Rails
Managing the transaction velocity where European house prices rise requires modern financial technology. Commercial lenders and mortgage aggregators are deploying automated valuation models (AVMs), digital land registry APIs, and algorithmic credit underwriting platforms to assess collateral risk in real time. Technology specialists tracking smart real estate platforms and financial software follow innovations covered by InvestorBytes digital finance.
Concurrently, international property syndicates and cross-border buyers managing multi-currency deposits face banking delays. Forward-looking real estate funds and alternative housing developers are evaluating programmable liquidity systems and stablecoins to execute transparent, escrow-backed cross-border settlements, bypassing correspondent banking delays during high-volume property acquisitions detailed in international capital analyses.
Shifting residential real estate valuations and institutional mortgage syndications continue to influence liquidity conditions across major financial hubs, as regularly highlighted in continental market coverage.
Valuation Implications for Publicly Listed Real Estate Equities
The uneven pace at which European house prices rise creates distinct investment strategies for public equity managers. While diversified residential landlords in France and Germany navigate compressed yields and debt refinancing hurdles, real estate developers and building materials suppliers in Spain, Portugal, and Eastern Europe benefit from firm asset valuations. Institutional equity research desks continuously evaluate net asset value (NAV) discounts, loan-to-value (LTV) ratios, and rental yield spreads across publicly traded securities documented by InvestorBytes equity intelligence.
According to formal residential housing data published by Eurostat, persistent construction material shortages and urban permitting delays suggest that structural supply deficits will continue to underpin valuations across high-demand metropolitan zones.
Corporate treasurers and real estate investment managers also monitor institutional debt issuance and commercial property trends directly through the InvestorBytes publication.
As prospective buyers navigate elevated borrowing costs, the data showing how European house prices rise confirms that Europe’s residential market is defined by national fundamentals. Driven by structural housing deficits and resilient household incomes in the South and East against interest rate sensitivity in the North and West, the continental real estate landscape remains deeply divided.
Disclaimer:
The information provided in this article is for educational, journalistic, and informational purposes only and does not constitute real estate, financial, legal, or investment advice.