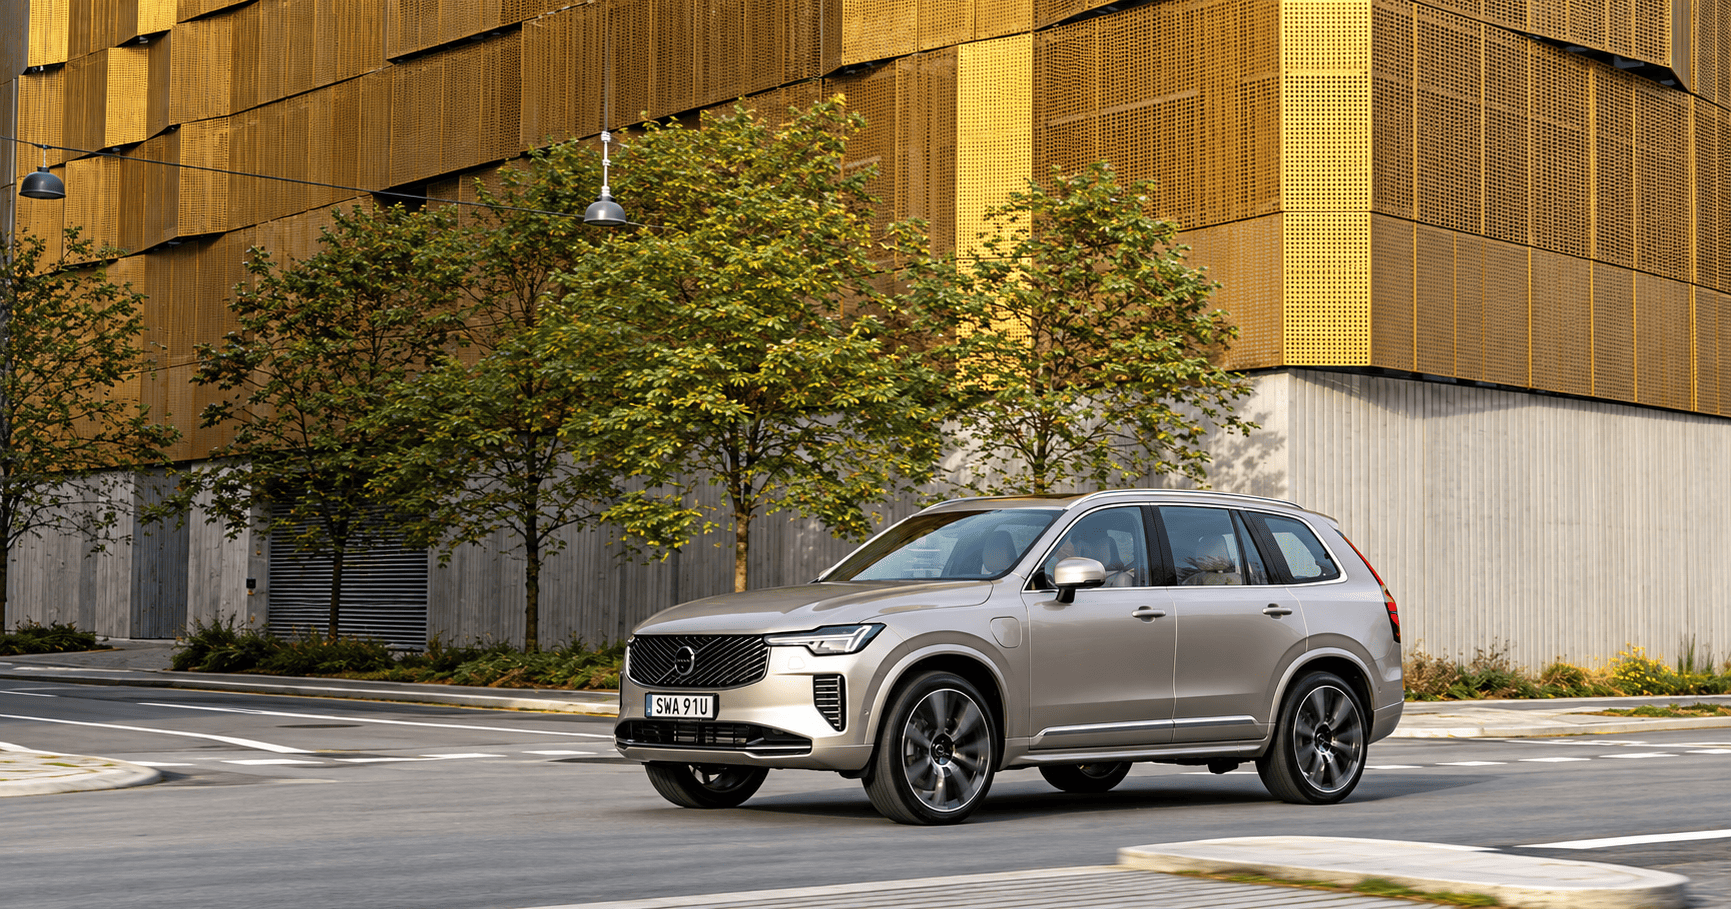
A severe reality check swept across the global premium automotive industry on Friday as Volvo Cars pulls sales guidance and abandoned annual cash flow forecasts, citing deteriorating commercial demand across Mainland China and an anemic recovery in the United States. In an unscheduled regulatory disclosure published from its Gothenburg headquarters, the Swedish luxury automaker majority-owned by China’s Zhejiang Geely Holding Group confirmed that previously established full-year retail volume and free cash flow targets were no longer achievable. The market response was immediate and punishing: shares of Volvo Cars dropped as much as 4% in early Stockholm trading to an all-time low of 14.60 Swedish crowns, bringing year-to-date equity losses to approximately 50%.
The sudden profit warning highlights the intensifying structural challenges confronting legacy Western automakers attempting to manage capital-intensive electric vehicle transitions amid escalating geopolitical trade barriers. Squeezed by punitive import tariffs on Chinese-built battery platforms, soft consumer appetite for pure electric models, and elevated software development outlays, Volvo’s operational margins have deteriorated rapidly. For automotive credit analysts, equity strategists, and corporate treasurers tracking how multinational manufacturers restructure capital expenditure during industrial demand shocks, regular newsroom reporting on business & finance provides essential intelligence on modern corporate governance.
Dissecting the Breakdown: China Weakness and US Headwinds
The primary catalyst forcing the automaker’s hand as Volvo Cars pulls sales guidance is an accelerating volume contraction in its two largest non-European markets. In a detailed operational statement, the company revealed that retail sales contracted to 141,609 vehicles during the third quarter, representing a sharp 11% year-on-year drop:
- The Chinese Market Deterioration: Prolonged domestic discounting and an aggressive price war among native Chinese new-energy vehicle brands have severely eroded Volvo’s premium market share in the mainland, with management noting that the structural downturn shows no signs of abating.
- Sluggish American Premium Demand: High consumer financing rates and consumer retrenchment have restrained recovery across the US luxury automotive space, preventing anticipated second-half volume rebounds.
- Resilient European Deliveries: In contrast to Asian and North American headwinds, European regional deliveries remained relatively steady, cushioned by corporate fleet renewal programs and hybrid powertrain demand.
- The Withdrawn July Forecast: As recently as July, executive leadership had guided for significantly stronger retail volumes in the second half of the year, alongside substantial positive free cash flow generation by the fourth quarter targets that have now been scrapped without updated numbers provided.
“This is partly expected because we’ve seen that the market has been very tough,” noted Handelsbanken equity research analyst Hampus Engellau, underscoring that institutional analysts had already begun discounting management’s optimistic guidance.
Automotive retail contractions, factory retooling delays, and corporate balance sheet strain directly alter consumer goods indices, manufacturing payrolls, and macroeconomic capital expenditure. Economists evaluating how industrial downshifts, protectionist tariffs, and shifting consumer demand reshape gross domestic output track structural indicators through dedicated coverage of the broader economy.
Leadership Overhaul: Klaus Zellmer Inherits an Uphill Battle
The crisis emerging as Volvo Cars pulls sales guidance arrives during an executive transition period. Last month, Volvo announced that former Škoda chief executive Klaus Zellmer would take over the chief executive officer position within a year, tasked with orchestrating a commercial turnaround.
Zellmer will inherit an automaker burdened by complex cross-border supply chains. While Geely’s ownership initially provided manufacturing scale and cost-efficient modular EV architectures, it has increasingly exposed Volvo to protectionist crossfire. The European Union’s countervailing duties on Chinese-manufactured electric cars and Washington’s 100% tariffs on Chinese EV imports have disrupted Volvo’s international assembly logistics, including deliveries of its flagship EX30 electric crossover.
Trade barriers, cross-border tariff disputes, and statutory vehicle emissions mandates remain contentious topics across international diplomatic assemblies. Observers monitoring how legislative bodies and ministerial cabinets shape foreign investment rules follow policy developments via politics.
Software Architectures, Telematics, and Supply-Chain Settlements
Overcoming the operational obstacles highlighted as Volvo Cars pulls sales guidance requires modernizing vehicle engineering. Premium carmakers are deploying centralized software compute platforms, over-the-air firmware updates, and algorithmic battery health management to remain competitive against aggressive Asian competitors. Technology specialists tracking smart mobility platforms and automotive software integration follow technical developments through specialized reporting on tech.
Concurrently, multinational automotive supply consortiums and tier-one component providers managing complex multi-currency assembly networks face significant payment friction. Corporate automotive treasuries are evaluating programmable liquidity systems and crypto networks to execute transparent, escrow-backed cross-border settlements for specialized raw materials, bypassing correspondent banking delays during international logistics disruptions.
Shifting automotive production schedules and trade frictions continue to drive volatility across European equity and corporate debt markets.
Equity Realities for Publicly Listed Automotive Equities
The dramatic valuation plunge occurring as Volvo Cars pulls sales guidance provides critical context for global portfolio allocators. Established automotive peers such as Mercedes-Benz Group, BMW, and Stellantis have similarly suffered multiple compression and margin degradation as the Chinese premium auto market shifts to domestic champions. Institutional equity research desks continuously evaluate vehicle price realizations, dealer inventories, and capital expenditure across publicly traded automotive stocks.
According to formal market tracking and corporate governance reports published by Nasdaq Stockholm, industrial transparency through timely guidance revisions remains critical to maintaining public shareholder confidence during unexpected cyclical downturns.
As incoming CEO Klaus Zellmer prepares his turnaround strategy, the reality that Volvo Cars pulls sales guidance confirms that the global electric vehicle transition is entering a more sober phase. Trapped between a relentless price war in China, slow US premium adoption, and rising trade barriers, the Swedish automaker faces a rigorous test to restore profitability and shareholder trust.
Disclaimer:
The information provided in this article is for educational, journalistic, and informational purposes only and does not constitute financial, investment, automotive procurement, or legal advice.